📊 Full opportunity report: When Does Cheap Memory Come Back? The 2027–2029 Question on ThorstenMeyerAI.com — validation score, market gap, and execution plan.

Turn your quiet moments into listening time
- Thousands of audiobooks, podcasts and originals
- Listen on your phone, tablet or Echo — also offline
- Cancel anytime
TL;DR
Memory shortages are projected to persist until at least late 2028, with prices stabilizing or declining slightly afterward. Industry capacity growth is slow, and demand remains high, especially from AI applications.
Memory prices are expected to remain elevated until at least late 2028 or early 2029, with industry insiders warning that a return to pre-crisis affordability is unlikely within the near term. The delay is driven by physical capacity constraints and sustained demand, particularly from AI infrastructure, making relief a long-term prospect rather than an imminent event.
Analysts and memory manufacturers such as Samsung, SK Hynix, and Micron project that the memory shortage will continue into 2027, with a genuine easing of supply and prices unlikely before late 2028. The primary bottleneck is the time-consuming process of building and ramping new fabrication plants, which can take several years from planning to production. Notable capacity additions, like Micron’s Idaho fab and SK Hynix’s Indiana plant, are expected to come online between 2027 and 2028, but the largest planned facility, Micron’s Clay megafab, has been delayed until 2030.
Market forecasts suggest that prices will stabilize at levels 30–50% above pre-crisis prices, reflecting a new normal rather than a temporary spike. Industry insiders emphasize that even with increased capacity, structural constraints—such as the bottleneck in advanced packaging and the discipline of manufacturers to avoid overbuilding—will keep prices high for years.
When does cheap memory come back?
The question everyone’s really asking: do I just wait this out? The honest answer is a timeline, three scenarios, and news you may not want — the cheap memory you remember isn’t coming back. A less-expensive market probably is — later, and at a higher floor.
Capacity ramps ’27–’28; price climbs stop, then ease. Settles ~30–50% above pre-crisis — the new baseline, not a return to 2024.
AI keeps accelerating; OpenAI locked ~40% of DRAM through 2029; makers pause expansion to protect record margins; each HBM gen worsens the math.
AI demand moderates just as delayed ’27–’28 fabs all arrive → classic overshoot → prices crash. Not the bet — but never impossible in this industry.
The one relief valve that needs no fab is efficiency: if compression (Part 9) cuts how much memory each model needs, demand softens on the timescale of a software update, not a construction project. So the posture isn’t waiting — it’s the discipline this series has been about. Memory is now a scarce, valuable resource; treat it that way. Buy what you need, right-size, own what’s steady, rent what’s spiky, quantize either way. The people who do best won’t be the ones who guessed the bottom — they’ll be the ones who stopped needing so much. That’s the squeeze, end to end.
Implications for Consumers and Industry Investment
For consumers, this means ongoing high prices for memory components used in PCs, servers, and data centers. For industry players, the delayed relief impacts supply chain planning, pricing strategies, and investment decisions. The persistent scarcity also influences the pace of AI development and deployment, as high memory costs can slow innovation and adoption.
Products Worth Considering

Hyperice Normatec Elite Wireless Compression Boots, Standard Size

Levoit Vital 100S-P Air Purifier
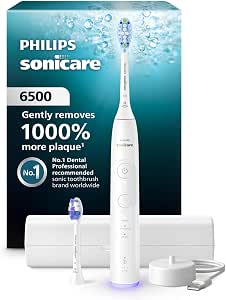
Philips Sonicare 6500 Rechargeable Electric Toothbrush with 2 Brush Heads, White
As an affiliate, we earn on qualifying purchases.
Physical and Market Factors Behind the Delay in Relief
The core reason for the delayed easing is the physical limitation of manufacturing capacity. Building new fabs, especially those capable of producing advanced HBM memory, requires years of planning, construction, and ramp-up. The industry’s capacity increases are concentrated in 2027 and 2028, with some of the largest projects, like Micron’s Clay fab, pushed to 2030. Meanwhile, demand for memory, driven by AI and data center growth, remains robust, further tightening supply.
Historically, the memory industry has experienced boom-bust cycles, with prices crashing only after oversupply occurs. However, current structural features—such as limited packaging capacity and manufacturers’ cautious expansion—are preventing oversupply and price drops in the near term.
“The industry expects the shortage to extend through 2027 and beyond, with significant easing not before late 2028.”
— Samsung spokesperson
Uncertainties in Capacity and Demand Growth
While projections point to late 2028 or 2029 for relief, uncertainties remain regarding the pace of capacity ramp-up, potential shifts in AI demand, and technological advancements that could alter manufacturing efficiency or memory consumption. Unexpected industry disruptions or demand fluctuations could further delay or accelerate the timeline.
Upcoming Capacity Expansions and Market Monitoring
Key developments to watch include Micron’s Clay fab completion in 2030, the deployment of US CHIPS Act-funded fabs, and any shifts in AI memory demand. Industry analysts will continue to monitor capacity additions, pricing trends, and demand signals to refine the timeline for memory price normalization.
Key Questions
When can I expect memory prices to drop significantly?
Most industry experts expect a meaningful decline in prices no earlier than late 2028 or 2029, once new capacity ramps fully and demand stabilizes.
Will the memory shortage ever end?
While shortages are likely to ease over time, the current structural constraints suggest that memory prices will remain higher than pre-crisis levels for several years, creating a new normal.
What factors could accelerate relief?
Potential improvements include faster capacity expansion, technological breakthroughs reducing manufacturing time, or demand reduction through efficiency gains in AI models and caching techniques.
How does AI demand influence the memory market?
AI applications continue to drive high memory demand, especially for high-bandwidth memory like HBM. Persistent AI growth keeps supply tight and prices high, delaying relief unless demand growth slows or memory becomes more efficient.
Source: ThorstenMeyerAI.com